Single Digit Growth Projected for US Janitorial Industry During Next 5 Years
Heightened hygiene standards and regulatory requirements are supporting industry growth
September 3, 2026
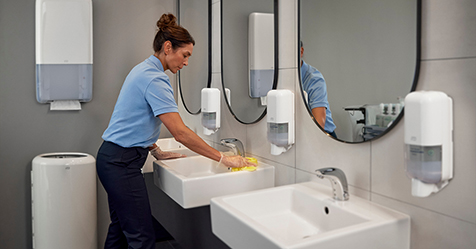
During the past five years, the janitorial services industry has expanded amid intense competitive pressure and shifting customer expectations, IBISWorld’s Janitorial Services in the U.S. report found. A surge of new entrants rushed in to capture post-pandemic demand, driving establishment growth faster than revenue and leaving providers to fight over contracts in a highly fragmented market. Clients, particularly businesses, have pushed hard on pricing and treated cleaning as a cost center even as they requested more frequent or specialized services, tightening the squeeze on providers. At the same time, higher labor costs have limited profit growth as many companies struggle to pass on rising expenses. Revenue has grown at a compound annual growth rate (CAGR) of 2.7% during the past five years and is expected to reach US$112.4 billion in 2026, with revenue rising by an estimated 1.7%.
Some individuals have recently entered the janitorial services space to capture new revenue streams driven by heightened concerns about cleanliness among businesses and households. The growing demand has encouraged more individuals and small operators to launch janitorial businesses, even as cleaning budgets have increased modestly. Establishments and enterprises have grown at a steady rate since 2021, markedly faster than revenue growth. While clients want more frequent cleaning, they still negotiate on price and treat janitorial services as a cost to be contained. As of 2026, over 1.2 million janitorial service establishments operate in the U.S.
Stringent cleanliness demands and tech innovations are reshaping the janitorial landscape, offering new growth avenues. Janitorial companies are aligning their services with these evolving norms while leveraging internet-connected devices and robotics to enhance efficiency.
Additionally, climate concerns and shifts in consumer preferences are accelerating the push for eco-friendly cleaning products. Larger businesses are most likely to invest in green alternatives, while smaller providers may trim nonessential expenses to meet environmental standards and changing customer expectations.
Looking ahead, the industry’s trajectory will be shaped by the continued normalization of hybrid work models alongside more consistent in-office attendance. Many companies have steadier building utilization and reinforcing demand for commercial cleaning as employers prioritize visible hygiene and workplace experience. At the same time, hybrid work remains embedded in corporate strategy, leading organizations to optimize and, in some cases, reduce their real estate footprints.
Portfolio consolidation, space reconfiguration, and selective office closures continue to influence demand patterns. Janitorial providers benefit from more predictable occupancy in active spaces but must adapt to leaner office portfolios, shifting usage patterns, and a growing emphasis on flexible, demand-responsive service delivery. They stand to benefit from increased activity in occupied spaces but must adjust to variable traffic patterns and greater demand for flexible, usage-based service models. Over the next five years, revenue is forecast to grow at a 2.0% CAGR, reaching $124.1 billion in 2031.
Latest Articles
Sponsored Articles